How to Stop Wasting Money and Start Saving More
Managing money is not always about earning more. Sometimes, the real problem is how we spend what we already earn. Many people work hard every month, pay their bills, buy groceries, and manage other expenses, but still find it difficult to save money.
Have you ever checked your bank balance near the end of the month and wondered where all your money went? You are not alone. Small daily expenses, unnecessary shopping, food deliveries, and unused subscriptions can quietly take a big part of your income.
The good news is that you do not need to make huge sacrifices to improve your finances. A few simple changes in your spending habits can help you save more and feel more confident about your financial future.
1. Understand Where Your Money Goes
Before changing your spending habits, take some time to understand them.
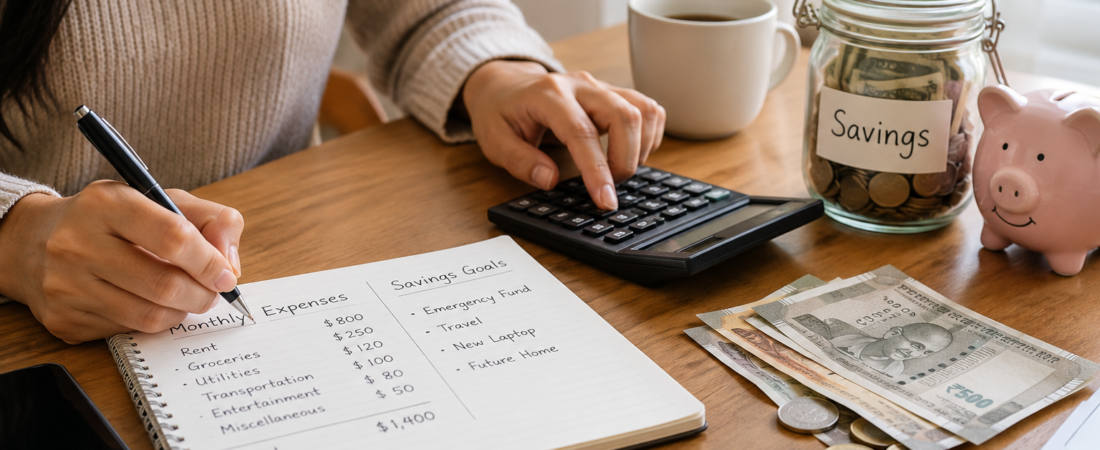
For one month, write down your expenses. Include everything, from rent and electricity bills to small purchases like snacks, coffee, and online shopping.
You may discover that some expenses are necessary, while others are simply habits. For example, buying a coffee occasionally may not affect your budget much. Buying it every day without planning, however, can become a noticeable expense over time.
You can track your spending using a notebook, a spreadsheet, or a budgeting app. The method does not matter as much as being consistent.
2. Separate Needs from Wants
One of the easiest ways to control spending is to understand the difference between needs and wants.
Needs are things you must pay for, such as food, housing, basic clothing, transportation, and essential bills. Wants are things that make life enjoyable but are not always necessary, such as expensive gadgets, frequent restaurant meals, or buying clothes you rarely wear.
There is nothing wrong with enjoying your money. The goal is to make sure that your wants do not take money away from important financial goals.
Before buying something, ask yourself a simple question: “Do I really need this, or do I just want it right now?”
Sometimes, waiting a day or two is enough to realise that you do not need the item.
3. Create a Monthly Budget
A monthly budget gives your money a clear purpose. Instead of spending first and saving whatever remains, you can decide in advance how much to spend and how much to save.
Start by calculating your monthly income after taxes and other deductions. Then list your fixed expenses, variable expenses, debt payments, and savings goals.
You can also try the 50/30/20 budgeting rule as a starting point:
- 50% for needs: Housing, groceries, utilities, and essential transportation.
- 30% for wants: Entertainment, dining out, hobbies, and non-essential shopping.
- 20% for savings and debt repayment: Emergency savings, financial goals, and additional debt payments.
These percentages are only a guideline. If your income is limited or your essential expenses are high, adjust the amounts to suit your situation.
A realistic budget is much more useful than a perfect budget that you cannot follow.
4. Avoid Impulse Buying
Online shopping has made buying things easier than ever. With a few clicks, you can order clothes, electronics, and other products without thinking much about the cost.
The problem begins when purchases are driven by emotions rather than actual needs.
Try using a 24-hour waiting rule for small non-essential purchases and a longer waiting period for expensive items. Add the product to your wishlist instead of buying it immediately.
You can also remove saved payment details from shopping websites, unsubscribe from promotional emails, and turn off shopping notifications.
These small barriers give you more time to think before spending.
5. Review Your Subscriptions
Subscriptions often seem inexpensive when viewed individually. However, several monthly payments can add up to a significant amount.
Check your bank statements for streaming services, paid apps, memberships, and other recurring charges.
Ask yourself three questions about each subscription:
- Do I use it regularly?
- Is it worth the amount I pay?
- Can I find a free or cheaper alternative?
Cancel the services you no longer need. Keep the ones that provide genuine value.
You do not have to remove every enjoyable service from your life. Just make sure you are paying for things you actually use.
6. Make Saving a Monthly Habit
Saving becomes easier when you treat it as a regular expense rather than something you do only when money is left over.
After receiving your income, move a manageable amount into a separate savings account. If possible, set up an automatic transfer.
You do not need to begin with a large amount. Even a small, consistent contribution can help you build the habit.
For example, saving ₹500 every month adds up to ₹6,000 over one year, before any interest. If your income increases later, you can gradually increase your savings as well.
The most important thing is to choose an amount you can realistically maintain.
7. Plan Your Shopping Beforehand
Unplanned shopping can lead to unnecessary spending, especially on groceries and household items.
Before visiting a supermarket or ordering groceries online, make a list of what you need. Check what you already have at home so you do not buy duplicate items.
Planning meals for the week can also reduce food waste and last-minute takeaway orders.
When comparing prices, look at the actual quantity and quality of a product rather than choosing something only because it has a discount label.
Remember, spending ₹1,000 on something you do not need is not saving money just because it was originally priced at ₹1,500.
8. Build an Emergency Fund
Unexpected expenses can disturb even a well-planned budget. A medical bill, urgent home repair, or temporary loss of income can force you to borrow money if you have no savings available.
An emergency fund provides a financial cushion for these situations.
Start with a small target, such as saving enough to cover one unexpected expense. Over time, work toward building savings that can cover three to six months of essential living expenses, depending on your circumstances.
Keep this money accessible and separate from the account you use for everyday spending.
An emergency fund is not built overnight. Regular contributions, even small ones, can help you move closer to your goal.
9. Be Careful with Credit Cards and Buy Now, Pay Later
Credit cards and buy-now-pay-later services can make purchases feel more affordable than they really are.
The risk is that several small payments can turn into a large monthly obligation. If you carry a credit card balance, interest and fees may make the original purchase much more expensive.
Before using credit, make sure you understand the repayment terms and can afford the purchase.
If you use a credit card, try to pay the full statement balance by the due date whenever possible. Avoid borrowing for unnecessary purchases simply because credit is available.
A purchase is not affordable just because you can pay for it in instalments.
10. Check Your Progress Every Month
Saving money is an ongoing process. Your income, expenses, and priorities may change, so your financial plan should change with them.
At the end of each month, review three things:
- How much money did you spend?
- How much did you save?
- What could you improve next month?
Do not feel discouraged if you miss a goal. Instead, look for the reason and make a practical adjustment.
Maybe your grocery budget was too low, or an unexpected expense affected your savings. Understanding what happened will help you make a better plan next time.
Progress does not have to be perfect to be meaningful.
Final Thoughts
Stopping unnecessary spending does not mean giving up everything you enjoy. It means making thoughtful decisions about where your money goes.
Start with one or two changes. Track your expenses, avoid impulse purchases, review your subscriptions, and save a small amount regularly. Once these habits become part of your routine, managing money may feel less stressful.
Remember, building a better financial future is not only about how much money you earn. It is also about how wisely you use it.
Start small, stay consistent, and give your money a purpose.
Frequently Asked Questions (FAQs)
1. What is the easiest way to stop wasting money?
Start by tracking your expenses for one month. Identify unnecessary purchases and recurring charges, then set a realistic spending limit for them.
2. How can I save money on a low income?
Focus on essential expenses first, plan your shopping, avoid unnecessary debt, and save a small amount regularly if your budget allows. Even a modest saving habit can be useful.
3. How much money should I save every month?
There is no single amount that works for everyone. The 50/30/20 rule suggests saving and debt repayment with 20% of income, but you can start with a smaller percentage and increase it when possible.
4. How can I control impulse buying?
Wait before making non-essential purchases, remove shopping notifications, and compare the purchase with your monthly budget. This gives you time to decide whether you genuinely need the item.
5. Why is budgeting important?
Budgeting helps you understand your spending, prepare for upcoming bills, build savings, and work toward financial goals without relying entirely on guesswork.
Disclaimer: This article is for educational and informational purposes only. Personal financial decisions should be based on your individual income, expenses, and circumstances.