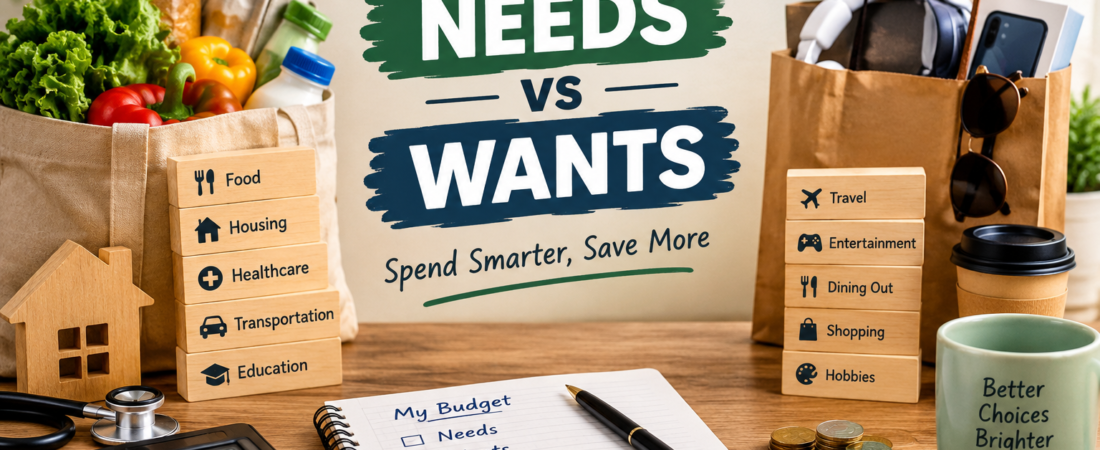
Have you ever gone shopping for a few essential items but returned home with things you never planned to buy? Maybe you went out to purchase groceries and ended up buying new clothes, ordering food, or spending money on something you saw online.
It happens to many of us. Sometimes, we spend money without thinking about whether we really need something or simply want it.
This is where understanding the difference between needs and wants becomes important. When you know how to separate the two, managing your money becomes easier. You can pay your bills on time, save more for the future, and still enjoy the things you love.
In this article, we will explain what needs and wants mean, how they affect your budget, and how you can make smarter spending decisions in everyday life.
What Are Needs?
Needs are the things you must have to live a healthy, safe, and reasonably comfortable life. Without them, it can become difficult to manage your daily activities or maintain your basic well-being.
Most people spend a significant part of their income covering these essential expenses.
Common examples of needs include:
- Food and water: Basic groceries and drinking water to stay healthy.
- Housing: Rent, mortgage payments, or other essential housing costs.
- Clothing: Basic clothes suitable for everyday life and the weather.
- Healthcare: Necessary medicines, medical appointments, and health-related expenses.
- Utilities: Electricity, water, heating, and essential household services.
- Transportation: The cost of getting to work, school, or other important places.
- Education and communication: Essential educational expenses and phone or internet access when needed for work, study, or daily responsibilities.
For example, buying groceries for the week is generally a need because you require food every day. Paying your electricity bill is also a need because electricity supports many basic household activities.
However, not every purchase in these categories is automatically a need. Buying basic clothes may be necessary, but purchasing an expensive designer outfit when you already have enough suitable clothes may be a want.
The purpose is not to spend as little as possible on necessities. It is to make sure your essential expenses are covered before spending money on less important things.
What Are Wants?
Wants are the things you would like to have but can live without. They may make your life more enjoyable, convenient, or entertaining, but they are generally not essential for meeting your basic needs.
There is nothing wrong with having wants. Money is not only for paying bills; it can also be used to enjoy life. Problems usually begin when wants take up so much of your income that you struggle to pay essential expenses or save for future goals.
Some common examples of wants include:
- Buying the latest smartphone when your current phone works properly.
- Eating at expensive restaurants when you could prepare food at home.
- Purchasing branded clothes even when you already have enough.
- Paying for several entertainment subscriptions you rarely use.
- Buying decorative items that you do not really need.
- Taking an expensive holiday that is outside your current budget.
- Upgrading your laptop or television simply because a newer model is available.
Imagine that you already have a good pair of shoes for everyday use. You see another pair online and decide to buy it because the design looks attractive. If your existing shoes are still suitable, the new pair is probably a want rather than a need.
Wants are not bad purchases. The important thing is to understand their place in your budget and make sure they do not interfere with your financial priorities.
Needs vs Wants: Key Differences
The main difference between needs and wants is the role they play in your life and how important they are to your financial well-being.
| Needs | Wants |
|---|---|
| Essential for everyday living | Improve comfort, enjoyment, or convenience |
| Usually require priority in your budget | Can often be delayed |
| Include basic food, housing, and healthcare | Include luxury meals, premium gadgets, and extra entertainment |
| Often have a deadline or regular payment date | Usually offer more flexibility in timing |
| Should generally be covered first | Should fit within the money remaining after priorities |
Keep in mind that the difference is not always clear. A purchase that is a want for one person may be a genuine need for another because of their job, health, location, or family responsibilities.
For example, a reliable laptop might be essential for someone who works remotely, while an expensive gaming laptop may be an optional upgrade for someone whose current computer already meets their needs.
Why Is It Important to Understand Needs and Wants?
Understanding the difference between needs and wants can help you take better control of your finances without feeling that you must stop enjoying life.
1. It Helps You Control Unnecessary Spending
Small purchases can add up over time. Buying coffee every day, ordering food frequently, or making unplanned online purchases may seem harmless individually. However, these expenses can become a significant amount over a month.
When you pause before making a purchase, you have an opportunity to decide whether the item is genuinely important or simply something you want at that moment.
2. It Makes Budgeting Easier
A budget gives every part of your income a purpose. When you know which expenses are essential and which are optional, you can plan your money more realistically.
You can set aside money for rent, groceries, transportation, and bills first. After covering these expenses and accounting for savings and debt payments, you can decide how much to spend on entertainment or shopping.
3. It Helps You Save for Future Goals
Saving money can be difficult when every extra amount gets spent immediately. By reducing unnecessary purchases, you may be able to build an emergency fund, save for education, plan a holiday, or work towards buying a home.
You do not need to eliminate every want. Even a small amount saved consistently can help you make progress towards your goals.
4. It Can Reduce Financial Stress
Unexpected expenses are easier to handle when you have some savings available. If most of your income goes towards optional purchases, you may find yourself struggling when your car needs repairs or a medical bill arrives.
Prioritising needs and building savings can give you more financial flexibility when life does not go according to plan.
How to Separate Needs From Wants in Daily Life
Knowing the definitions is easy. Applying them while shopping or making everyday decisions takes practice.
Here are some simple ways to get started.
1. Ask Yourself Three Questions Before Buying
Before purchasing something, take a moment to ask:
- Do I genuinely need this item right now?
- Can I manage without it for the next few weeks?
- Will buying it affect my bills, savings, or other financial goals?
If you can comfortably delay the purchase, it may be worth waiting before making a decision.
2. Make a List Before Shopping
Going shopping without a plan can lead to unnecessary purchases. Before visiting a supermarket or shopping online, write down the items you actually need.
Once you have bought those items, think carefully before adding anything else to your cart.
This simple habit can help you avoid spending money just because something is on sale.
3. Follow a Monthly Budget
At the beginning of each month, write down your expected income and expenses. Separate essential costs from optional spending so you can see where your money is going.
For example, your budget could include:
- Essential expenses such as rent, groceries, and bills.
- Savings and debt repayments.
- Personal spending for entertainment, eating out, and hobbies.
The exact amounts will depend on your income, cost of living, and responsibilities. A budget should reflect your real circumstances rather than an unrealistic spending target.
4. Use the 24-Hour Rule
If you want to buy something that is not essential, wait at least 24 hours before making the purchase. For expensive items, you may want to wait several days or even a few weeks.
During that time, ask yourself whether you still want the item and whether it fits your budget.
Sometimes, the excitement of buying something fades after a little time has passed. Waiting gives you a chance to make a calmer decision.
5. Watch Out for Discounts and Online Offers
A discount does not automatically mean you are saving money.
Suppose a jacket originally costs $100 and is now available for $70. You have not saved $30 if you did not need the jacket in the first place. You have still spent $70.
Before taking advantage of an offer, ask yourself whether you would have purchased the item without the discount.
6. Review Your Spending at the End of Each Month
Look through your bank statements, receipts, or spending notes. Identify purchases that were useful and those you could have avoided.
Do not use this exercise to blame yourself for every unnecessary expense. Instead, look for patterns you can improve next month.
For example, if frequent food deliveries are using more money than expected, you could plan a few easy meals at home each week.
Needs vs Wants: A Real-Life Example
Let’s consider a person who earns $2,000 per month after tax.
Their monthly budget might look like this:
| Expense | Monthly amount |
|---|---|
| Rent and utilities | $700 |
| Groceries | $300 |
| Transportation | $150 |
| Healthcare and essential bills | $100 |
| Savings | $250 |
| Debt repayment | $150 |
| Eating out and entertainment | $150 |
| Shopping and other wants | $100 |
| Miscellaneous expenses | $100 |
| Total | $2,000 |
This is only an illustrative example. Actual costs and appropriate savings amounts will differ from person to person.
Notice that the budget includes money for both financial priorities and enjoyment. The goal is not to remove all wants from your life. It is to keep spending within your means while taking care of your responsibilities.
If this person wants to increase their savings, they could review their restaurant spending or optional shopping first. They should also check whether their essential expenses are already as reasonable as possible before making further cuts.
A budget works best when it is realistic enough to follow consistently.
The 50/30/20 Budget Rule and Needs vs Wants
The 50/30/20 budget rule is one method people use to organise their income.
Under this approach, you aim to divide your after-tax income into three broad categories:
- 50% for needs: Essential expenses such as housing, groceries, utilities, and necessary transportation.
- 30% for wants: Optional spending such as hobbies, dining out, entertainment, and non-essential shopping.
- 20% for savings and debt repayment: Money for savings goals and additional debt repayments, depending on your circumstances.
For example, if your monthly take-home income is $2,000, the guideline would allocate $1,000 to needs, $600 to wants, and $400 to savings and debt repayment.
These percentages are guidelines, not strict rules. In a city with high housing costs, your needs may take up more than 50% of your income. If you have significant debt or are building an emergency fund, you may decide to adjust the other categories.
The important thing is to use a budget that works for your actual financial situation.
Common Mistakes People Make When Managing Needs and Wants
Even when people understand the difference, a few habits can make it difficult to manage money effectively.
Treating every purchase as a necessity: Sometimes, we justify purchases because they are useful or convenient. However, something can be useful without being essential.
Ignoring small expenses: A few inexpensive purchases may not seem important, but repeated spending can add up over time.
Comparing your lifestyle with others: Friends, colleagues, and social media can create pressure to buy things you do not really need. Your financial decisions should be based on your income and goals, not someone else’s lifestyle.
Cutting out every enjoyable expense: A budget that allows no room for personal enjoyment may be difficult to maintain. Setting aside a reasonable amount for wants can make your financial plan more sustainable.
Forgetting irregular expenses: Annual insurance payments, home repairs, school expenses, and other occasional costs can disrupt a budget if you do not plan for them. When possible, set aside money for these expenses in advance.
Avoiding these mistakes can help you create a more balanced approach to spending and saving.
Final Thoughts
Understanding needs vs wants is a simple but valuable step towards better money management. It helps you recognise which expenses deserve priority, where you have room to make changes, and how your daily choices affect your long-term financial goals.
You do not need to stop buying things you enjoy or feel guilty whenever you spend money on yourself. Instead, focus on making thoughtful decisions, paying for essentials first, and saving regularly according to your circumstances.
Start with one small change this month. Review your expenses, identify one unnecessary purchase, and redirect that money towards a goal that matters to you.
Over time, these small decisions can help you develop healthier spending habits and feel more confident about managing your money.
Remember, good money management is not about buying nothing. It is about knowing what matters most and spending your money accordingly.
Frequently Asked Questions (FAQs)
1. What is the main difference between needs and wants?
Needs are essential for everyday living, such as food, housing, and necessary healthcare. Wants are things that make life more enjoyable but can generally be delayed or avoided without affecting basic needs.
2. Is a mobile phone a need or a want?
It depends on the situation. A basic phone may be a need if you rely on it for work, education, safety, or essential communication. Buying the latest expensive model when your current phone works properly is usually a want.
3. Is eating at a restaurant a need or a want?
Eating is a need, but eating at a restaurant is often a want because you may be able to prepare food at home. However, restaurant meals can be necessary in some situations, such as when travelling or when cooking facilities are unavailable.
4. How can I spend less money on wants?
Set a monthly limit for optional spending, avoid impulse purchases, unsubscribe from services you rarely use, and wait before buying expensive items. Reviewing your spending regularly can also help you identify areas where you can save.
5. Should I completely stop spending money on wants?
No. Wants are a normal part of life, and spending on hobbies, entertainment, and personal interests can be enjoyable. The key is to make sure optional spending fits your budget and does not interfere with essential expenses, debt obligations, or savings goals.
6. How does understanding needs and wants help with saving money?
It helps you identify expenses you can reduce without compromising your basic needs. You can then direct the money you save towards an emergency fund, future purchases, debt repayment, or other financial goals.
7. What is the 50/30/20 budget rule?
The 50/30/20 budget rule is a budgeting guideline that suggests allocating 50% of after-tax income to needs, 30% to wants, and 20% to savings and debt repayment. You can adjust these percentages to suit your income and circumstances.