How to Figure Out Your Income: A Simple Guide for Beginners
Money gets messy fast, doesn’t it? You might see a salary printed on your payslip, but most folks forget about side cash, bonuses, or random freelance gigs. It adds up. Before you know it, planning or saving feels more like throwing darts blindfolded.
But getting a handle on your income isn’t hard. Break it down step by step, and you’ll see exactly what’s coming in—and what you can actually use.
What Counts as “Income”?
When people say income, they just mean any money you make. Doesn’t matter if it’s from a job, a side hustle, investments, or those online sales you do every now and then.
- Regular job salary or hourly wages
- Freelance gigs or contract work
- Business profits (after expenses!)
- Rent you collect
- Investment returns or bank interest
- Commissions or bonuses
- Earnings from selling things online
Basically, if it shows up in your account (or your wallet) from work you did or something you own, it’s income.
Step 1: Start with Your Main Job
First, look at your main paycheck. Your payslip has two important numbers:
Gross income: What your job pays before anything gets taken out.
Net income: What actually lands in your bank after taxes and deductions.
So, if you see ₹40,000 up top and ₹4,000 in deductions, you’re actually getting ₹36,000.
That net figure? That’s what you build your budget around.
Step 2: Add Side Money
These days, plenty of us do more than one thing for cash. Maybe you tutor, maybe you sell art, maybe you drive for a rideshare app. Add up all the extra earnings, whatever they are.
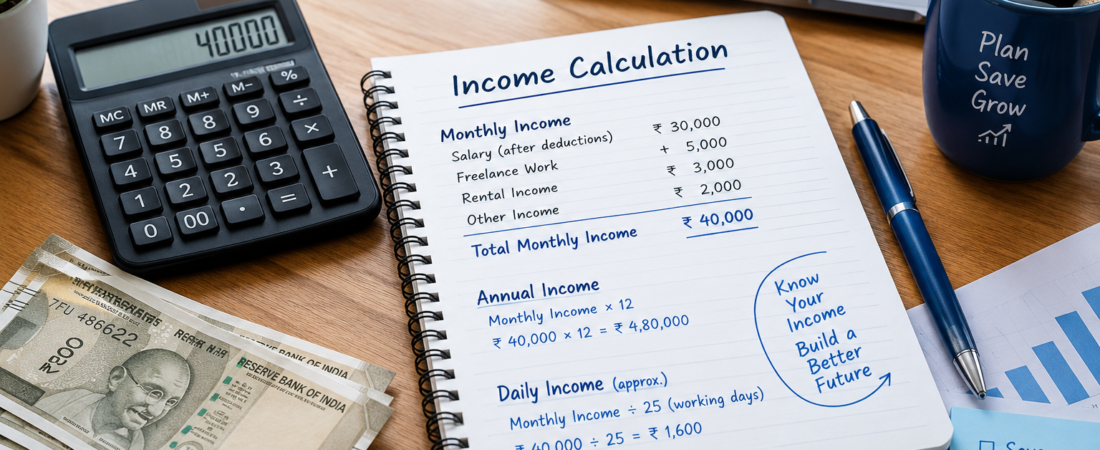
Here’s an example breakdown:
Salary (after deductions): ₹30,000
Freelance design: ₹5,000
Online surveys: ₹2,000
Rent from a flatmate: ₹3,000
Total monthly income: ₹40,000
If you run a business, remember—DON’T count every sale. Only your profit (sales minus costs) is real income.
Step 3: Work Out Your Annual Income
For most people, annual income is just monthly income times 12.
So, if you make ₹35,000 per month, you’re looking at ₹4,20,000 a year.
If you get bonuses, add those on top of your normal total.
Remember: gross and net are pretty different, so don’t mix them up.
Step 4: Break It Down Smaller
Maybe you get paid weekly, or by the day. In that case:
Weekly income = (Monthly income × 12) ÷ 52
Daily income = Monthly income ÷ working days in the month
So, with ₹30,000 a month and 25 working days:
₹30,000 ÷ 25 = ₹1,200 per day
Just keep in mind, real life isn’t tidy. Some days you earn less, other times more.
Step 5: Don’t Confuse Profit with Revenue
Got a business or side gig? This is key. If you make ₹50,000 in sales, but spend ₹23,000 on goods, shipping, and ads, your profit is ₹27,000. That profit is what you can actually use.
Step 6: Add It Up for the Whole Household
If you share bills with someone else, add everyone’s net income to find the total you all have to work with.
You: ₹35,000
Partner: ₹25,000
Other sources: ₹2,000
Total: ₹62,000 a month
Having the full picture helps you budget for rent, groceries, bills—everything that matters.
Step 7: See What’s Left After Bills
You need to know not just what you bring in, but what you keep. Subtract your regular spending from your take-home income.
Example:
Income: ₹35,000
Expenses: ₹27,000
Leftover: ₹8,000
That’s what you can save, invest, or use for big goals—or just have as a buffer.
Watch out for sneaky, less-frequent bills—insurance renewals, annual subscriptions—that can eat into your leftover money.
Step 8: Track Your Money Each Month
It’s way easier when you write things down. Pen and paper, spreadsheet, budgeting app—pick whatever’s easiest.
Jot down:
- When you got paid
- The source of the income
- The amount
- Any taxes or expenses taken out
- Your monthly total
Is your income unpredictable? Average out the last six months, just to keep things real. Plan for the low months—it’ll save you a headache later.
Mistakes to Avoid
- Forgetting about taxes and deductions
- Skipping your side hustles
- Adding up all business sales instead of just the profit
- Counting money moved between your own accounts
- Leaving out big, rare bills
- Using last year’s numbers instead of updating regularly
Review your numbers every so often. It’s worth it.
To Wrap Up
Figuring out your income doesn’t need to be complicated. List every cent you earn, take out the costs and taxes, and you’ll see your real, usable money.
If you run a business, keep revenue and profit separate—otherwise it all gets messy fast. Once you’ve nailed down your actual income, compare it to what you spend. That way, you know how much you can save or use for what matters to you.
You don’t need fancy apps or finance degrees. A little habit and a few notes each month are all it takes to get ahead.
FAQs
- How do I find my monthly income?
Add up your main take-home pay and any extra money you bring in each month. If you’re self-employed, only count your profit. - What about annual income?
Multiply your monthly income by 12. Don’t forget to tack on any big bonuses or random windfalls. - What’s the difference between gross and net income?
Gross is what your job or clients pay before taxes. Net is what you actually get to use. - I work for myself—how do I figure out my income?
Add up everything you earn, subtract all legit business expenses, and the rest is your profit. - How do I handle irregular income?
Add up your earnings from several months and divide by the number of months. Six or twelve months is a good window. - Why bother with all this?
Because once you know what you’re truly earning, everything from budgeting to saving gets way easier.
(Quick note: This is just a general guide. Taxes and rules shift depending on where you live and your particular situation.)