Handling money rarely feels simple, right? Your salary shows up, but somehow, it disappears faster than you expect—between bills, groceries, and the urge to splurge a little. You always hear advice: “Save more!” or “Stop spending!” Sounds nice, but actually doing it? Whole different story.
That’s where the 50/30/20 rule comes in. People like it because it doesn’t make things complicated. You just split your take-home pay three ways: needs, wants, and savings or debt.
No need to fire up a monstrous spreadsheet or pretend you’re a financial wizard. If you’ve got a basic idea of where your cash is going, this rule helps you keep spending under control without driving yourself nuts.
So what’s the 50/30/20 rule in plain English?
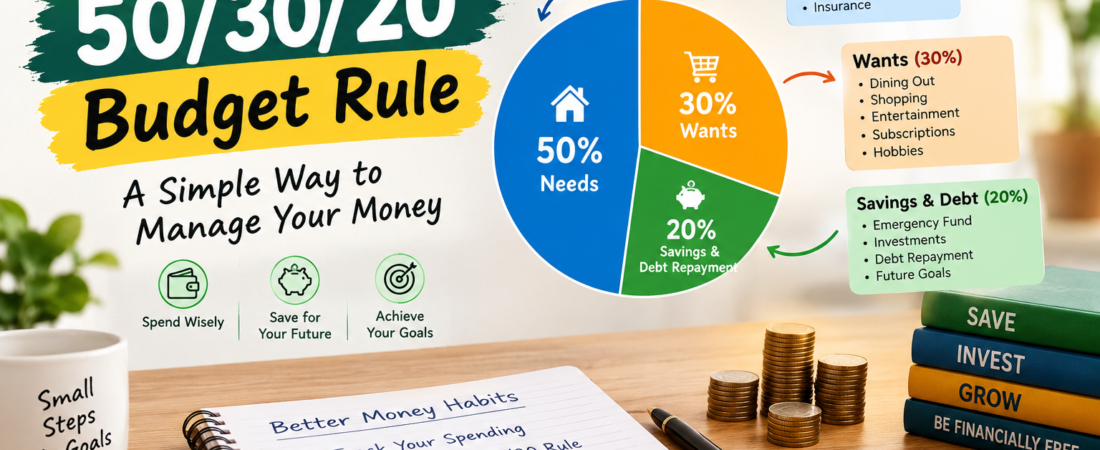
Here’s how you break it down:
- 50% for Needs
- 30% for Wants
- 20% for Savings or Debt
Let’s say you bring home ₹40,000 a month. Your budget could look like this:
Needs: ₹20,000
Wants: ₹12,000
Savings & Debt: ₹8,000
You don’t need to nail these numbers down to the rupee—they’re more of a starting point.
50% for Needs
Half your money should go toward must-haves: rent, food, bills, insurance, the stuff you literally can’t ditch. If you earn ₹40,000, aim to keep essentials around ₹20,000. But life has other ideas, sometimes. Maybe your city’s pricey or expenses keep popping up that you can’t avoid.
Honestly, the exact percentage isn’t the point. Knowing what you’re spending—that’s what matters.
30% for Wants
Next comes the fun: movies, restaurants, new clothes, hobbies, that tenth streaming service. Don’t beat yourself up about spending here. Ignore all the experts who act like fun is the enemy of financial peace. Cut out everything that makes life enjoyable and, eventually, you’ll just quit budgeting.
For ₹40,000, you get about ₹12,000 for wants. If you don’t spend it all, cool—roll over the rest into savings or chip away at debt.
20% for Savings and Debt
This part is about building your future—emergency funds, investments, retirement, paying off high-interest debt. With ₹40,000, 20% lands at ₹8,000. Can’t hit that right now? No worries. Start small—showing up matters more than hitting the full 20% on day one.
What if your monthly income is ₹50,000? Here’s the split:
Needs — ₹25,000
Wants — ₹15,000
Savings/Debt — ₹10,000
Again, you’re not stuck with these—it’s just a way to gauge where your money’s going.
But what if your needs eat up more than 50%?
For lots of people, they do. Maybe you take home ₹30,000, but rent and other basics swallow up ₹20,000—that’s over two-thirds, not half. Take a breath. You’re not failing. The 50/30/20 rule is a baseline, not a rulebook. Maybe your numbers look more like 60/20/20 or 70/15/15. As you earn more, or cut some expenses, try to rebalance.
Paying Down Debt
If you’re battling a big loan or a scary credit card balance, focus your “savings and debt” slice on wiping it out. Don’t skip building a small emergency stash—life happens—but kill off costly debt as fast as you can. How you divide that last 20% will depend on interest rates, what kind of debt it is, and how much security you need.
Is the 50/30/20 rule good for beginners?
Absolutely. That’s why it’s popular. No need to log every coffee or every little snack. You just ask yourself:
- What must I pay for?
- What do I want to buy?
- How much am I saving or using to pay off debt?
Once you break it down that way, budgeting seems a lot less intimidating.
How to Get Started with the 50/30/20 Rule
Here’s your roadmap:
- Check what actually hits your bank account, after taxes and deductions.
- Jot down last month’s real spending—dig through bank statements, apps, or even your wallet.
- Label each expense: is it a need, a want, or savings/debt?
- Stack up your spending against the 50/30/20 guide.
- If you’re way off somewhere, pick one thing to adjust. Don’t go for a total overhaul overnight.
And one hack: automate savings if your bank lets you. Shift the money to another account the moment you get paid, and you’re less likely to raid it later.
Common Budgeting Traps
- Trying to force your life into a perfect 50/30/20 split. That’s not realistic—tweak as needed.
- Overlooking daily “little” spends. Hundreds here and there vanish fast.
- Pretending “wants” are “needs.” Going out to eat is a want—not the same as groceries when the fridge is empty.
- Forgetting about those rare but big expenses—insurance renewals, holiday shopping, gifts, repairs. Budget for them so they don’t sneak up on you.
Can you change the rule?
Definitely. 50/30/20 isn’t set in stone. Maybe your needs are high now. Maybe you throw more at savings when you get a raise. The point? Shape your budget to fit your reality.
Final Thoughts
At the end of the day, this rule isn’t there to make you feel bad or stressed. It just helps you see your money clearly and steer it toward what matters most. The percentages are there to get you moving—they’re not the law.
The budget that works is the one you’ll actually keep using. Adapt it, make it yours, and start small if you need to. The important thing is to know where your money’s going and choose your priorities on purpose.
FAQs
Is the 50/30/20 rule for everyone?
Not always, but it’s flexible. Tweak it for your situation.
Does the 20% include investments?
It does—savings, investments, or extra debt payments all fit here.
What if I can’t save 20%?
That’s fine. Even a little is better than nothing. Increase when you can.
Should rent count as a need?
Of course—rent, electricity, and basic living costs all go here.
What if my income changes every month?
Just budget with a safe estimate, and adjust when things shift. Being flexible is key.